

India’s Solar Cell Growth to Boost Metallization Paste Demand: Interview
DKEM aims to expand India operations with customized solar metallization pastes
October 12, 2026

Follow Mercom India on WhatsApp for exclusive updates on clean energy news and insights
India’s expanding solar cell manufacturing capacity and the rising preference for n-type TOPCon cells are creating significant opportunities for metallization paste and, particularly, technologies that can reduce both silver consumption and production costs.
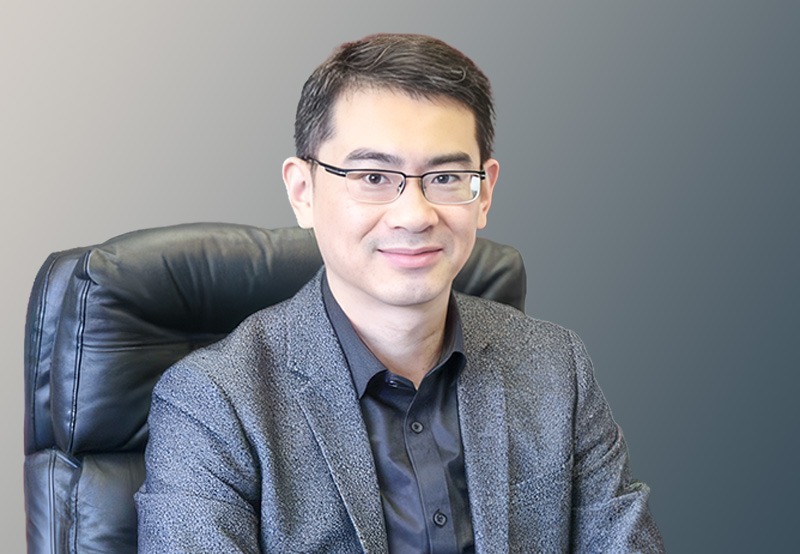
In an exclusive interview with Mercom India, Weili Shi, Chairman and General Manager at DK Electronic Materials (DKEM), talks about the company’s India strategy, plans to expand customized silver pastes and local technical support team, and its development of low-silver-content, silver-coated copper, and pure copper metallization technologies.
Edited excerpts from the interview:
What are DKEM’s plans and priorities for its solar business in India?
DKEM is the world’s largest supplier and technology leader of metallization pastes for the solar industry and has supported the transition from p-type to n-type solar cells, as well as developments in Laser Enhanced Contact Optimization (LECO) and silver-coated copper metallization.
DKEM aims to support manufacturers with product technology and process engineering expertise while expanding its market presence. We are already engaged with Adani, Premier Energies, Avaada, Waaree, Tata Power Solar, Emmvee, RenewSys, Grew Solar, Alpex Solar, Goldi Solar, Saatvik Solar, Evervolt, Gopin and Jupiter. Our local channel partner supports customer coordination and on-site service across manufacturing hubs.
How does DKEM assess the opportunity created by India’s expanding solar cell manufacturing capacity, and what are its plans for manufacturing, R&D, technical support, or other investments in the Indian market?
India’s solar cell manufacturing capacity is expected to grow from roughly 30 to 35 GW toward 100 GW by the end of 2027, increasing the demand potential for metallization pastes. The industry is also shifting from p-type PERC to n-type TOPCon. DKEM’s products are already in mass production at several Indian cell manufacturers. It has established India-focused sales and technical teams and works with a local channel partner for logistics and on-site coordination.
The company plans to deepen customer collaboration, expand local technical support, and set up a dedicated R&D team to develop process-specific customized pastes.
How are policies such as ALMM List-II and India’s broader push for domestic solar manufacturing influencing DKEM’s strategy for the Indian market?
ALMM List-II and India’s domestic manufacturing push are accelerating localization across the solar value chain. Equipment choices, process recipes, and material specifications may differ from other markets. DKEM plans to work more closely with Indian cell manufacturers and accelerate development of customized silver pastes for local process, performance, cost, and compliance requirements..
Silver paste remains critical to solar cell manufacturing. What technology developments is DKEM pursuing to reduce silver consumption while maintaining cell efficiency, reliability, and production yields?
DKEM is pursuing four silver-reduction pathways: fine-line printing, low-silver-content pastes, silver-coated copper pastes, and pure copper pastes. For G12R TOPCon cells, many Chinese lines use about 70 to 80 mg of silver paste per cell, while many Indian lines use about 85 to 100 mg. DKEM expects advanced fine-line printing and customized pastes to narrow this gap while maintaining efficiency, reliability, and yields. Its technical teams also support process optimization and qualification at customer sites.
Which of DKEM’s products are most critical for high-efficiency solar cell manufacturing today?
For TOPCon cells, DKEM highlights three products. The DK72E front-side finger paste is optimized for LECO technology and is designed to significantly reduce metallization-induced recombination while improving contact quality. The DK95E rear-side finger paste is compatible with PECVD and LPCVD poly-Si processes. The DK82E busbar paste is designed for solderability and reliability. The combination supports outstanding conversion efficiency, a wide process window, and long-term reliability.
As India adds new solar cell manufacturing capacity, which silver paste, low-silver, and copper-based metallization products does DKEM expect to see the strongest demand for in the Indian market?
DKEM expects near-term demand to focus on mature silver pastes and proven silver-reduction methods, particularly fine-line printing using advanced screen technologies and customized pastes. Copper-based solutions require additional capital expenditure, process changes, and longer validation cycles. DKEM therefore expects low-silver-content and silver-coated copper pastes to gain adoption as manufacturers progress through further efficiency and reliability validation.
With silver remaining a major cost component in cell manufacturing, how much can low-silver and silver-copper metallization technologies reduce cell production costs?
The savings depend on each production line’s starting silver consumption. Fine-line printing and customized silver pastes can reduce silver consumption per watt by more than 30% from current Indian baselines. Low-silver-content pastes can provide further reductions. Silver-coated copper metallization on the rear side of TOPCon cells can reduce silver use by about 50%.
What potential does DKEM see for copper-based paste to replace silver in solar cell metallization, and what technical challenges must be overcome for large-scale commercial adoption?
DKEM sees copper as a major long-term alternative to silver and divides the technology into silver-coated copper and pure copper pastes. DKEM’s silver-coated copper metallization solution is already in mass production on the rear side of TOPCon cells with a global customer. Broader adoption of copper-based metallization will require further progress in performance, cost, and reliability. Key technical areas include the synergistic optimization of paste formulations and sintering techniques to minimize copper oxidation and enhance grid line conductivity; the development of simpler, more cost-effective process equipment and conditions; and the assessment and management of copper diffusion risks. DKEM also identifies interconnectionand encapsulation as relevant to managing reliability risks.
How is silver price volatility influencing DKEM’s R&D priorities and the development of lower-silver or copper-based paste technologies?
Silver reduction has been a research priority even before the recent rise in silver prices considering the sustainability of the solar industry. Its roadmap covers fine-line printing, low-silver-content pastes, silver-coated copper pastes, and pure copper pastes. Higher silver prices have increased the urgency of commercializing these technologies, particularly for manufacturers seeking lower metallization costs.
Beyond current TOPCon applications, how is DKEM preparing its metallization technology for HJT, back-contact, tandem, and other next-generation solar cells?
Beyond TOPCon, DKEM has developed silver-coated copper pastes for heterojunction cells that are already used at industrial scale. For TBC ( TOPCon Back Contact) cells, it offers pastes for n-Poly, p-Poly, and busbar applications. For perovskite and silicon tandem cells, DKEM is developing and offering ultra-low-temperature curing pastes. Its conductive pastes and electronic adhesives can also serve semiconductor packaging, display, and advanced electronics applications in India.
This interview was sponsored by DKEM

Parth Shukla
More articles from Parth Shukla.