

India Added 6.6 GW of Rooftop Solar Capacity in 1H 2026
The country added 3.8 GW of rooftop solar systems during Q2 2026
August 27, 2026

Follow Mercom India on WhatsApp for exclusive updates on clean energy news and insights
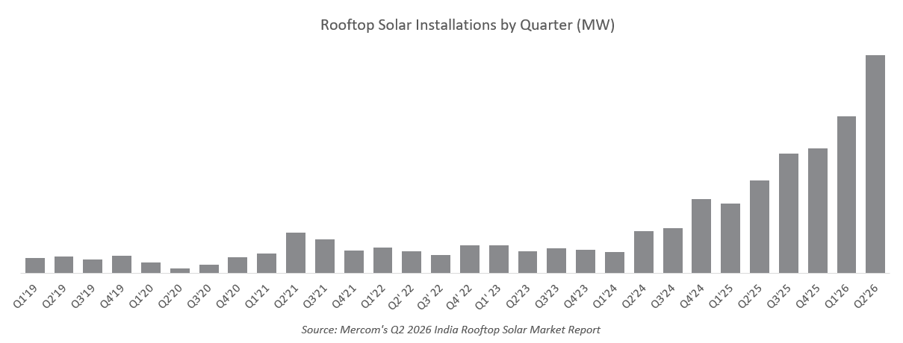
India added 6.6 GW of rooftop solar capacity in the first half (1H) of 2026, up 131% year-over-year (YoY) from 2.8 GW, according to Mercom India Research’s newly released Q2 and 1H 2026 India Rooftop Solar Market Report.
In the second quarter (Q2) of 2026, rooftop solar installations totaled 3.8 GW, up 136% YoY from 1.6 GW and 39% quarter-over-quarter (QoQ) from 2.7 GW.
Rooftop solar accounted for 33% of India’s total solar installations during the quarter.
The growth was driven primarily by the government’s continued push under the PM Surya Ghar: Muft Bijli Yojana. Rooftop solar systems had been installed at nearly 4.5 million households as of June 2026, reaching approximately 45% of the program’s target of 10 million households.
The residential segment accounted for 84% of total rooftop solar additions during Q2 2026. Industrial installations accounted for 10%, commercial installations for 5%, and government installations for 1%.
Installations under the capital expenditure model accounted for 84% of the quarterly additions.
“India has a strong residential rooftop solar pipeline, but converting it into installations will depend on faster approvals, financing, and project delivery. Higher grid tariffs should strengthen commercial demand, but rising system costs and regulatory constraints could limit industrial growth. The Approved List of Models and Manufacturers (ALMM) transition window will help projects move forward in the second half, but it could also trigger a rush to meet deadlines and increase price volatility. Beyond 2026, market growth will depend on domestic cell capacity ramping up quickly and states removing approval, metering, and grid connectivity bottlenecks,” said Raj Prabhu, CEO of Mercom Capital Group.
ALMM and DCR Module Prices
The implementation of ALMM List-II requirements from June 1, 2026, increased pressure on domestic solar cell availability and Domestic Content Requirement (DCR) module prices.
Subsequent transition measures eased some near-term pressure, with eligible net-metering and open access projects receiving an extension until December 31, 2026.
Residential consumers under PM Surya Ghar opting for the “Give It Up” category can forgo the subsidy and use non-DCR modules until the program ends in March 2027.
Average rooftop solar system costs remained broadly flat during Q2 2026, although prices varied significantly by module technology and sourcing. Systems using Chinese Mono PERC modules were the least expensive, while systems using Indian TOPCon DCR modules were the most expensive.
The price differential has become increasingly significant as domestic content requirements drive demand for compliant solar cells and modules.
According to Priya Sanjay, Managing Director at Mercom India, the transition to domestically manufactured solar cells will affect all market segments. Until domestic cell manufacturing capacity catches up with module demand, the market could face a shortage of DCR-compliant modules and higher module prices. The temporary regulatory relief announced by the government could offer some support, but DCR module availability is likely to remain a near-term concern.
On the commercial and industrial (C&I) segment, Sanjay said its lower share partly reflects the rapid expansion of residential rooftop installations. She added that uncertainty over regulatory requirements and rising DCR module prices delayed project decisions. C&I consumers generally take a few months to approve proposals, and projects quoted before the transition could face significantly higher costs if required to switch to DCR modules. As a result, some consumers delayed approvals while awaiting clarity on possible extensions.
Top Three States
Uttar Pradesh, Maharashtra, and Gujarat led rooftop solar capacity additions during Q2 2026, accounting for 18%, 15%, and 13%, respectively.
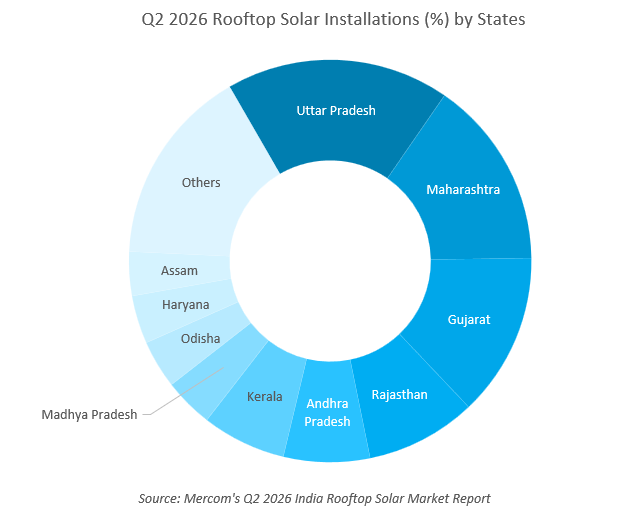
The top 10 states accounted for 80% of cumulative rooftop solar installations as of June 2026. Gujarat, Maharashtra, Uttar Pradesh, Rajasthan, and Kerala led in cumulative installed capacity.
Between Q2 2025 and Q2 2026, Assam registered the highest compounded quarterly growth rate at 36%. Uttar Pradesh followed at 23%, while Andhra Pradesh recorded 20%.
Outlook
India’s rooftop solar market is likely to experience strong growth in 2026, with residential installations expected to remain the primary driver, supported by PM Surya Ghar and state-level incentives.
Commercial rooftop solar installations are also expected to grow significantly as higher grid tariffs improve potential savings from rooftop solar.
Industrial installations could face near-term challenges from comparatively lower grid tariffs, higher system and energy storage costs, and more stringent connectivity, net metering, banking, and other network requirements in some states.
Sanjay also highlighted skilled manpower availability as a growing challenge across the solar industry. With utility-scale, residential, and C&I installations expanding simultaneously, engineering, procurement, and construction companies, installers, and developers increasingly require trained personnel for project construction and execution. The industry has managed the shortage so far, but the challenge could intensify as deployment increases.
She said streamlined regulatory approvals could further accelerate rooftop solar installations. A single-window clearance mechanism would reduce delays, particularly for net metering approvals, which vary considerably across states. In some states, lengthy approval processes are restricting rooftop solar adoption. For C&I consumers, rooftop solar economics are already attractive because of electricity cost savings.
The report also includes a comprehensive analysis of net metering policies across all Indian states and union territories.
The Q2 and 1H 2026 India Rooftop Solar Market Report covers installations, market trends, state-level developments, system costs, investments, policies, and forecasts across India’s rooftop solar market. For the complete report, visit: https://www.mercomindia.com/product/rooftop-solar-market-report-q2-2026

Parth Shukla
More articles from Parth Shukla.